The wallet is moving from policy to implementation
The European Digital Identity Wallet is no longer just a policy topic. At the eIDAS Summit in Berlin on 28 and 29 April 2026, public and private stakeholders met to discuss EUDI Wallet implementation, pilot lessons and the next steps before wider European rollout.
For businesses, this matters because identity is not a back-office detail. It affects onboarding, fraud prevention, age checks, contract signing, account creation, customer recovery and access to regulated services.
The wallet promises a cleaner future: citizens and businesses sharing verified identity data digitally, with more control and less repeated document handling.
That future is attractive. But the transition will not be clean.
Businesses will need to support old and new identity methods at the same time
The arrival of the EUDI Wallet does not mean passports, ID cards, bank-based identification and local eID schemes suddenly disappear from onboarding flows.
Some customers will adopt wallet-based identity quickly. Others will not. Some markets will move faster than others. Some use cases will need qualified credentials. Others will still rely on document scans, bank-based ID, address validation or electronic signatures.
This is the practical problem for companies: they cannot design for one identity method and assume the market will follow.
- A Dutch customer may expect iDIN.
- A Belgian customer may use itsme.
- A German customer may follow a different route.
- A Nordic customer may be used to BankID.
- An international customer may only have a passport or residence document.
- A high-risk case may still require extra checks.
That is what onboarding will look like for a while: not one elegant route, but several routes that need to work without confusing the customer.
The real question is not “will the wallet matter?”
It will.
The better question is: can your onboarding process handle change without being rebuilt every time?
Many organisations have identity flows that grew one exception at a time. A new country was added. Then a new document type. Then a bank-based ID method. Then eSigning. Then AML screening. Then a manual review queue.
The result works, but only because teams know where the workarounds are.
That kind of setup becomes fragile when the identity market changes.
The EUDI Wallet adds another reason to clean this up. Not because every business needs to be wallet-first tomorrow, but because identity orchestration will become more important. Companies will need to route customers through the right method based on country, risk level, document availability, regulatory requirements and customer preference.
If that routing is hardcoded, slow or heavily manual, onboarding will suffer.
Good identity flows reduce uncertainty
A good onboarding flow does not ask every customer to do the same thing. It asks for the right level of assurance for the situation.
- A low-risk customer may need a simple identity confirmation.
- A regulated financial product may require stronger KYC.
- A gambling operator may need age verification and exclusion checks.
- A lease or financing journey may require identity plus affordability evidence.
- A contract flow may need an electronic signature that can be defended later.
The point is not to collect more data by default. The point is to collect the right data, at the right moment, with a clear reason.
That is where many onboarding flows go wrong. They ask too much too early, or they ask too little and create manual follow-up later. Both hurt conversion. Both create operational cost.
The wallet may reduce friction, but not all friction
The EUDI Wallet could remove some of today’s repeated identity work. If a customer can share verified credentials directly, businesses may need fewer document uploads and fewer manual checks.
But the wallet will not remove every business rule. Companies will still need to decide which credentials are acceptable, how consent is captured, when additional verification is needed, how fraud signals are handled and how the process is documented.
They will also need fallback routes. A customer without a wallet still needs to onboard. A cross-border customer may not have the expected credential. A document may still need to be verified. A signature may still be required.
So the practical goal is not to replace the current onboarding flow with “the wallet”. The goal is to build an onboarding process that can use the wallet where it helps, and use other methods where it does not.
What companies should review before the market shifts
Businesses do not need to wait for full EUDI Wallet adoption before improving onboarding. In fact, waiting may make the transition harder.
A useful review starts with five questions:
- Which identity methods do we support today? Include document scanning, bank-based ID, eID schemes, address validation and manual review.
- Where do customers drop off? Look for steps where users abandon the process, upload the wrong document or need support.
- Which checks are truly required? Separate regulatory requirements from habits that became part of the flow over time.
- Can we route customers by risk and context? A single fixed process is rarely the best process.
- Can we add a new identity method without rebuilding the journey? This is the wallet-readiness test that matters most. If adding a new method requires a long technical project, several manual workarounds and new support scripts, the architecture is probably too rigid.
Where Bluem fits
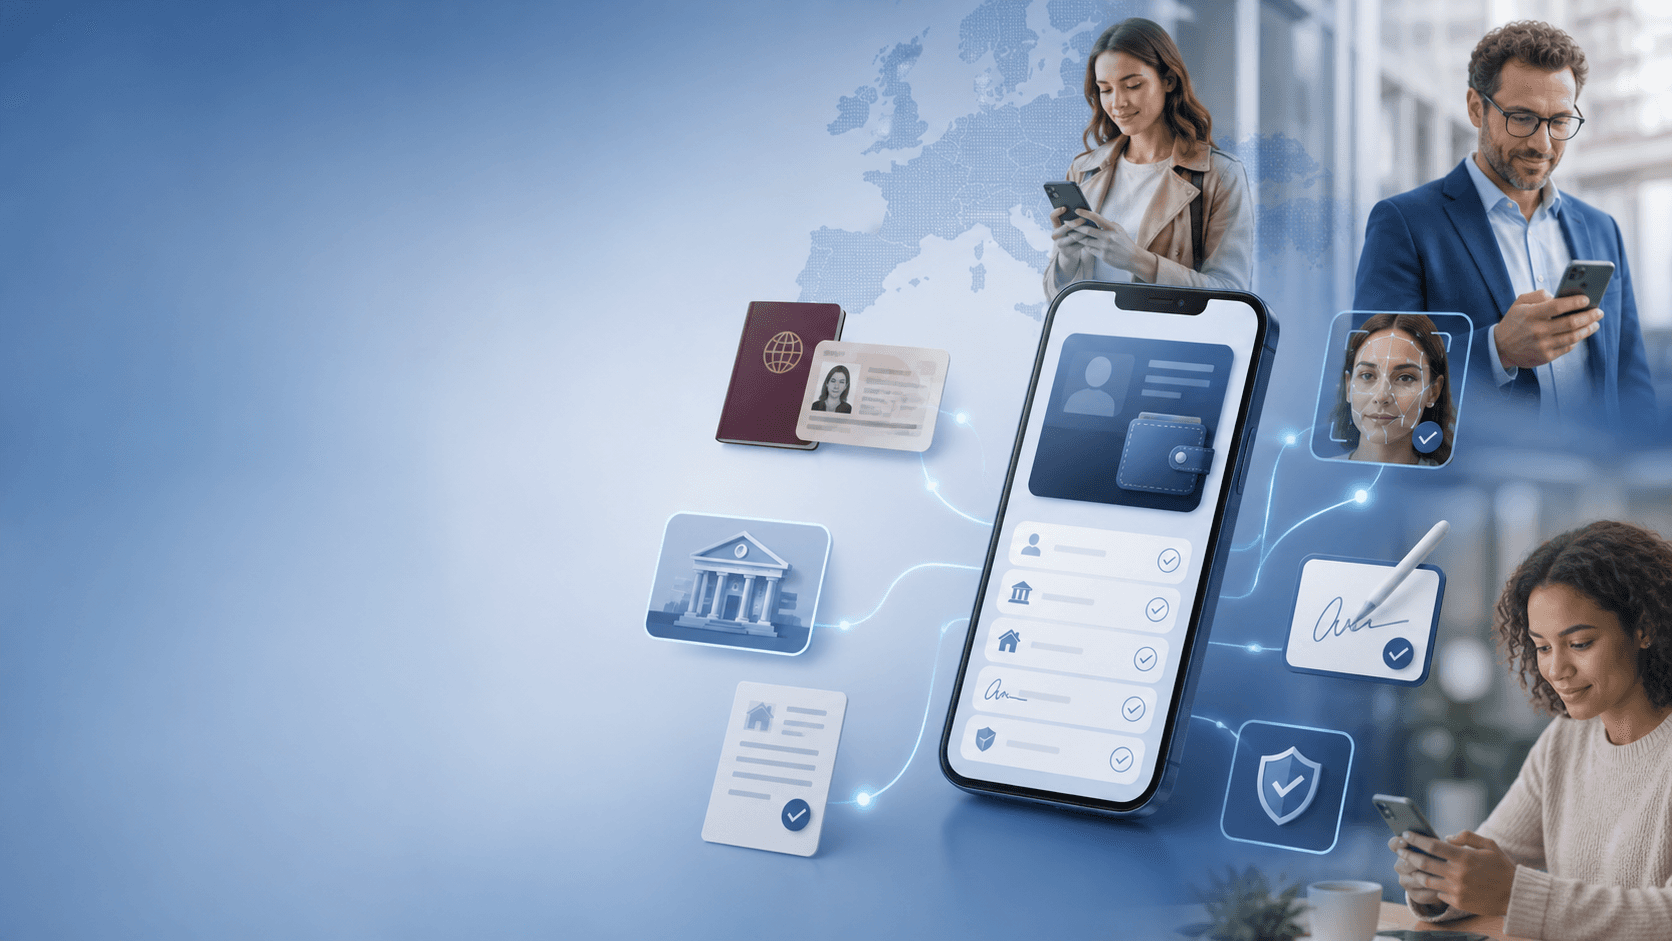
Bluem helps companies build onboarding flows that can handle multiple identity and trust methods in one process. That can include ID document verification, bank-based identification, address validation, eSigning and compliance checks.
The value is not in pushing every customer through the same path. It is in giving each customer a route that fits the situation while keeping the process manageable for the business.
That matters now because the identity market is changing. The EUDI Wallet will become part of the landscape, but it will sit alongside existing methods for some time.
Companies that prepare well will not be the ones that wait for a perfect European identity standard. They will be the ones that make their onboarding flexible enough to support today’s customers and tomorrow’s credentials.
Want to see where your onboarding flow may become a bottleneck? Bluem can help you review your current identity routes and prepare for wallet-based verification without breaking what already works.