Auteur/autrice : Équipe Bluem

  • The Future of Online Identification: Secure & User-Friendly

    L'avenir de l'identification en ligne : sécurisé et convivial

    We are doing more and more online: shopping, banking, and even important tasks such as getting a mortgage or registering for an event. However, these developments also bring new challenges. How can you as a business owner be sure that the person on the other side of the screen is truly who they say they are? And how do you ensure that this process remains safe and user-friendly?

    Online identification is the solution and forms the backbone of the modern digital economy. Services like iDIN and Checkin.com make it possible to verify identities reliably.

    Why online identification is becoming increasingly important

    With the growth of digital services, the need for secure and reliable authentication is also increasing. A copy of a passport is often vulnerable to fraud and phishing. Moreover, consumers want convenience: they expect quick access without endless forms or complexity. The presence of the user is no longer required – everything can be handled digitally in one seamless flow.

    Online identification services solve these problems by:

    • Security: Strong authentication prevents unauthorized access.
    • Privacy: Data is only shared with the user’s consent.
    • Speed: Simplifies processes and ensures an efficient user experience.
    • Certainty: Provides reliable verification of identities, giving both businesses and users confidence in the process.

    iDIN: The pioneer in secure online identification

    iDIN, developed by Currence, is one of the most widely used online identification services in the Netherlands. It uses the trusted login methods of banks, providing a high level of security and reliability.

    Comment fonctionne iDIN ?

    • The user selects iDIN as the identification method in an online environment.
    • Through their bank environment, the consumer logs in.
    • The consumer grants permission to share personal data.
    • The bank confirms the identity and shares this data securely with the provider, only with the user’s consent.

    With applications such as age verification (for example, when selling alcohol) and account creation, iDIN is already a proven solution. It provides entrepreneurs certainty about customer data and meets legal requirements.

    ID-Scanning: A Reliable Method for Online Identification

    ID-Scanning is an online identification method using a scan or photo of your identity document (such as a passport, driver’s license, or ID card). This approach is ideal for applications where a high level of certainty about identity is required, such as at financial institutions, landlords, or other services.

     How does ID-Scanning work?

    With ID-Scanning, identity documents can be digitally captured and checked, giving businesses assurance about their customers’ identities. The process begins with uploading a clear digital copy of an identity document, such as a passport, ID card, or driver’s license. The authenticity of the document is then analyzed using advanced technology, including artificial intelligence (AI) and machine learning. This technology checks security features such as watermarks and holograms and compares the data with relevant databases.

    If necessary, an additional manual review by a specialist can be conducted to identify irregularities or eliminate doubt. Thanks to this combination of automation and expert control, ID-Scanning offers a secure and efficient way to verify identities, providing confidence for both businesses and users. ID-Scanning is an efficient and safe method for verifying identities and is widely used in various sectors.

    What does this mean for your business?

    For entrepreneurs, it is clear: online identification is not a luxury but a necessity. Whether you work in e-commerce, healthcare, or finance, reliable and secure identification strengthens your customers’ trust and protects your business against risks.

    With identification solutions like iDIN and Checkin.com, you can easily adapt to this trend. Invest now in the future of online identification and prepare your business for a safe and customer-friendly digital world.
  • How to digitalize your business in 2025

    How to digitalize your business in 2025

    The Advantages of Digitalization

    1. Increased Productivity

    One of the main reasons for companies to digitalize is the gain in productivity. According to the McKinsey report, 56 percent of companies indicate that integrated digital technologies have significantly improved their work processes. By automating processes such as inventory management, customer service, and administration, organizations can maximize their resources. Especially in sectors like retail and business services, these improvements are significant.

    1. Better Customer Orientation

    Alongside productivity, digitalization enables companies to serve their customers better. With advanced data analysis tools, businesses can better understand and respond to customer behavior. More than 62 percent of companies in the retail sector reported that digital technologies helped them personalize customer interactions and increase loyalty.

    Challenges of Digitalization

    1. Lack of Qualified Personnel

    A shortage of skilled personnel remains a major challenge. The study reveals that 24 percent of companies struggle to find employees with the right digital skills. Smaller companies particularly suffer from this, as they have fewer resources to attract talent.

    1. Implementation Costs

    High costs are mentioned by 19 percent of companies as an obstacle to digitalization. For smaller companies, investments in software, hardware, and training often pose a significant hurdle.

    How to Start Digitalizing?

    For companies that want to start digitalizing, there are various practical steps that can be implemented in the short term. Here are three ways to begin digitalizing that offer relatively simple solutions:

    Digital Payments and Direct Debits: By switching to digital payment systems, transactions can be processed more quickly and securely.

    Digital Onboarding: including ID scanning and PEP/sanction list checks, ensures quick and secure verification of new customers and employees. These automated processes reduce the risk of fraud and ensure that companies meet compliance requirements.

    Digital Signing: Implementing digital signatures speeds up the approval process for documents and contracts. Additionally, digitalizing contracts simplifies and secures contract management and storage.

    Conclusion

    Digitalization in 2025 is not only about technology but also about strategy. By choosing the right tools and partners, companies can tackle both the opportunities and challenges of digitalization. Companies that invest timely in digital transformation lay the groundwork for a competitive and future-proof organization.

    Source: McKinsey & Company Digital Strategy Insights 2024

  • 4 tools every HR department will need in 2025

    4 tools every HR department will need in 2025

    The world of Human Resources is changing rapidly. What was once an administrative role is now a strategic function crucial to an organization’s success. Smart technology plays a key role in this transformation. With the right tools, you can work more efficiently and provide a unique employee experience. Bluem develops innovative solutions that meet the needs of modern HR teams. Here are four essential tools that will elevate your HR department.

    1. iDIN: Secure and Fast Identification

    Identifying employees, especially during onboarding, can be a time-consuming process. iDIN simplifies this by enabling secure and user-friendly digital identification. No more hassle with physical documents; everything flows smoothly and completely online.

    Benefits of iDIN:

    • Accelerate onboarding with digital identification.
    • Reduce paperwork and contribute to a sustainable workflow.
    • No need to ask for a passport copy.
    • Secure sensitive processes like contract signing.
    1. Real-Time IBAN-Name Check: Eliminating Payment Errors

    Entering bank details is error-prone and can lead to costly problems. The Real-Time IBAN-Name Check prevents these risks by instantly verifying if the data is correct. This minimizes errors and increases payment reliability.

    What does this tool offer?

    • Automatic verification of bank details without extra effort from employees.
    • Reduce risks of fraud and incorrect payments.
    • Save time by eliminating manual checks.
    • Bank card copy unnecessary.
    1. Scrive eSign: Smart and Digital Signing

    Signing documents no longer has to be a time-consuming task. With Scrive eSign, you can have contracts and other important papers digitally signed, legally binding and compliant with international standards.

    Why choose digital signing?

    • Reduce administrative hassle and make the process more efficient.
    • Work flexibly, even when participants are not physically present.
    • Ensure seamless onboarding, even remotely.
    1. PEP and Sanction List Checking: Fully Compliant Working

    In sectors where regulations play a major role, such as financial services, it is crucial to screen candidates. With Bluem’s automated PEP and Sanction List Checking, you ensure new employees comply with anti-money laundering laws and other requirements, ensuring they do not appear on a sanctions list.

    This tool offers:

    • Immediate screening on international sanctions lists and PEPs.
    • Real-time insights to timely signal risks.
    • Assurance that you comply with all laws and regulations.

    Transform the HR Department

    Efficiency, security, and compliance are the pillars of a modern HR strategy. With tools like iDIN, the Real-Time IBAN-Name Check, Scrive eSign, and PEP and Sanction List Checking, you can digitize outdated processes, minimize risks, and provide a streamlined employee experience.

    Bluem’s solutions help you be less dependent on paperwork and manual actions, optimally preparing your HR department for the future and making a lasting impression on employees and candidates.

  • KYC, what is it and why is it important?

    KYC, what is it and why is it important?

    In recent years, KYC (Connaître votre client) has evolved into a crucial business process within organizations. The aim? To thoroughly understand customers in order to minimize risks of financial crime and safeguard the integrity of the financial system.

    What is KYC?

    KYC, or “know your customer,” refers to processes by which financial institutions verify the identity of their clients and assess potential risks. Through thorough investigation, institutions can determine if a client is involved in criminal activities, such as money laundering, fraud, or financing terrorism. This process not only protects the financial institution but also the broader financial system.

    The KYC process includes:

    • Identification and verification of clients and any ultimate beneficial owners (UBOs).
    • Creating a complete customer profile.
    • Determining the purpose and nature of the customer relationship.
    • Identifying and assessing risks.
    • Analyzing transactions.
    • Accepting or rejecting clients based on research findings.

    KYC and CDD: What is the difference?

    KYC serves as an overarching principle that encompasses Customer Due Diligence (CDD) and Anti-Money Laundering (AML). Although the terms are often used interchangeably in practice, CDD specifically focuses on customer due diligence within the broader KYC framework.

    Importance of KYC

    Financial institutions such as banks and insurers are legally required to protect their services from criminal use. This means they must recognize and assess potential risks to prevent misuse.

    Complying with KYC rules not only contributes to the integrity of the financial system but also protects the reputation of institutions. Furthermore, it fosters trust in the economy, which is essential for stability.

    Legislation and Obligations

    In the Netherlands, KYC obligations are enshrined in various laws, including:

    1. The Anti-Money Laundering and Anti-Terrorist Financing Act (Wwft): Focuses on detecting and reporting unusual transactions.
    2. The Sanctions Act: Prevents business relations with sanctioned parties.
    3. The Financial Supervision Act (Wft): Provides oversight of the financial sector.

    This legislation is based on international recommendations from the Financial Action Task Force (FATF). Financial institutions are required to report unusual transactions to the Financial Intelligence Unit (FIU).

    Enforcement and Penalties

    In recent years, various institutions have been fined for shortcomings in KYC processes. For example, ING paid a settlement of 775 million euros for negligence in money laundering prevention, and Rabobank was fined a million euros for inadequate customer records.

    The Solutions by Bluem

    Bluem understands the challenges of KYC and offers various solutions to make the process more efficient, secure, and customer-friendly.

    Verifying the accuracy of an IBAN number is essential to prevent payment issues. With Bluem’s IBAN-Name Check, you can quickly and easily ensure that the account holder’s name matches the specified IBAN number. This reduces the risk of fraudulent transactions and mistakes.

    Bluem offers digital verification options allowing you to quickly and reliably confirm the identity of new clients. This helps meet legal requirements and reduces the risk of identity fraud.

    Protect vulnerable individuals from unwanted situations and contracts. The person should not independently enter into agreements or make financial decisions. In practice, it involves individuals suffering from mental disorders, overspending, or addictions. With Bluem’s CCBR check, a company prevents issues later on, including the financial damage associated with reversing all (null) actions.

    To comply with legal obligations related to anti-money laundering practices, it is crucial to conduct thorough customer checks. Bluem’s AML solution automates this process by screening clients against sanction lists, PEP lists (Politically Exposed Persons), and other relevant data sources. This helps companies to comply with regulations and minimize integrity risks.

    Conclusion

    KYC is indispensable in the fight against financial-economic crime. For financial institutions, this not only means fulfilling legal obligations but also contributing to a reliable and secure financial system.

  • Pourquoi de plus en plus d'entreprises passent à iDIN

    Pourquoi de plus en plus d'entreprises passent à iDIN

    Avec la croissance des services numériques, il devient de plus en plus important pour les entrepreneurs de pouvoir identifier rapidement et de manière fiable les clients. En même temps, les consommateurs attendent que ce processus soit sécurisé et convivial. iDIN Offre une solution innovante qui répond parfaitement à ces exigences. Pourquoi de plus en plus d’entreprises choisissent iDIN ? Et que fait-il de ce service d’identité indispensable pour vous en tant qu’entrepreneur ?

    Qu’est-ce que iDIN Et comment cela fonctionne-t-il ?

    iDIN est un service d’identification en ligne qui utilise les méthodes de connexion sécurisées des banques. Les utilisateurs peuvent confirmer leur identité et partager leurs données personnelles avec les entreprises via iDIN, sans avoir à créer de nouveaux comptes. La force d’iDIN réside dans la confiance que les utilisateurs accordent déjà à leur banque, combinée à un processus d’utilisation simple.

    Comment cela fonctionne-t-il ?

    1. L’utilisateur choisit iDIN comme méthode d’identification sur un service en ligne ou dans un e-commerce.
    2. Grâce à un environnement de connexion sécurisé propre à leur banque (comme c’est le cas avec la banque en ligne), l’utilisateur confirme son identité.
    3. Les données telles que le nom, l’adresse et la date de naissance sont partagées en toute sécurité avec l’entreprise, exclusivement avec le consentement explicite de l’utilisateur.

    Pourquoi les entreprises choisissent iDIN ?

    1. Assurance de l'identité du client

    En tant qu’entrepreneur, vous souhaitez vous assurer que vos clients sont bien ceux qu’ils prétendent être. Que ce soit pour vérifier l’âge, vérifier l’identité lors de transactions sensibles ou créer un compte – iDIN offre une solution simple et fiable. De cette manière, votre entreprise respecte également directement les exigences légales, comme pour la vente d’alcool ou d’autres produits soumis à un âge minimum.

    Par exemple : PostNL teste un système selon lequel les clients doivent prouver qu'ils ont plus de 18 ans en utilisant iDIN pour la livraison d'alcool. Cela simplifie et sécurise le respect des lois et réglementations.

    1. Facilité d'utilisation pour les consommateurs

    Un processus client fluide est essentiel pour la conversion et la satisfaction des clients. Avec iDIN, les consommateurs n’ont pas besoin de créer de nouveaux mots de passe ou de nouveaux comptes. Ils utilisent leur environnement bancaire de confiance pour vérifier leur identité. Cela réduit les obstacles et garantit une meilleure expérience client.

    1. Protection contre la fraude

    iDIN utilise une authentification robuste grâce aux systèmes de sécurité des banques. Cela minimise le risque de fraude et d’accès non autorisé. Pour les entrepreneurs, cela signifie moins de risques et un degré de confiance accru dans les données clients.

    1. Confidentialité et conformité

    iDIN a été conçu en gardant l’intégrité des données des consommateurs à l’esprit. Les entreprises reçoivent uniquement les données nécessaires à une transaction spécifique, et l’utilisateur donne expressément son consentement. Cela rend iDIN non seulement sécurisé mais également entièrement conforme au Règlement général sur la protection des données (RGPD).

    Applications d’iDIN

    La polyvalence de l'identification iDIN en fait un outil adapté à divers secteurs d'activité. Voici quelques exemples :

    • Verification de l'âgeVente d'alcool, de tabac ou d'autres produits soumis à des restrictions d'âge.
    • Création d'un compte: Registrement direct et sécurisé des nouveaux utilisateurs.
    • Services financiersConfirmer l’identité pour des demandes de prêt ou d’assurance.
    • Les clubs de footballPour les clubs de football professionnels, il est important de savoir exactement à qui ils vendent une carte de club.

    Comment fonctionne iDIN ?

    1. Choisissez iDIN comme méthode d'identification : Lorsque vous souhaitez vous identifier sur un site web qui prend en charge iDIN, sélectionnez l'option iDIN. Cela peut être dans un magasin en ligne, un service gouvernemental ou une compagnie d'assurance.
    2. Sélectionnez votre banque : Après avoir sélectionné iDIN, vous serez redirigé vers un écran où vous pourrez sélectionner votre banque. Ces dernières sont généralement les principales banques néerlandaises comme ING, Rabobank, ABN AMRO, etc.
    3. Connectez-vous à votre banque : connectez-vous ensuite à votre banque comme vous le feriez normalement pour le e-banking. Cela peut se faire via l’application de votre banque sur votre smartphone ou avec un code de sécurité physique.
    4. Confirmer votre identité : Une fois connecté, votre banque confirme votre identité auprès du prestataire de services auprès duquel vous souhaitez vous identifier. Il est important de noter que votre banque ne partage pas de données sensibles telles que votre numéro de compte ou votre solde avec le prestataire de services ; seule la confirmation de votre identité est transmise.

    Prêt(e) pour la prochaine étape ?

    Avec iDIN, votre entreprise devient plus efficace, sécurisée et conviviale envers les clients. Que ce soit pour se conformer aux exigences légales, augmenter les taux de conversion ou améliorer vos relations client – avec iDIN, vous bénéficiez d’une solution éprouvée.

    Vous souhaitez être prêt comme entrepreneur pour l'avenir ? iDIN est alors le choix idéal pour vous, car il met l'accent sur la confiance et la sécurité dans vos services.

  • Why More Organizations Are Starting with Digital Authorization for Collections

    Why More Organizations Are Starting with Digital Authorization for Collections

    Organizations are constantly seeking ways to optimize their processes. Digital direct debit authorization is a solution that is increasingly being embraced. It enables companies and customers to quickly and easily arrange permissions for recurring payments or authorizations. But what makes this approach so appealing, and why are so many organizations switching?

    Qu’est-ce que Digital Direct Debit Authorization?

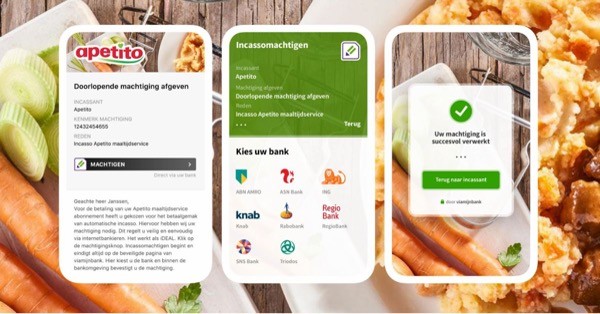
    Digital direct debit authorization is an online process that allows a customer to give an organization permission to automatically collect payments. This process is similar to an iDEAL transaction: the customer chooses their bank, gives approval, and the authorization becomes valid immediately. The traditional paperwork that used to be associated with authorizations is now a thing of the past.

    Benefits for Organizations

    More and more companies see the benefits of digital authorization. A key argument is the time savings. Where traditional authorizations could take days or even weeks due to mailing, processing, and manual checks, a digital authorization can be completed in just a few minutes.

    Additionally, digital authorization offers a greater degree of accuracy. Because the data is entered and processed directly through the customer’s bank, errors such as incorrect account numbers or missing information are virtually eliminated. This prevents administrative issues and improves the quality of the customer relationship.

    Another major advantage is compliance. Digital direct debit authorization complies with legal requirements and guidelines surrounding automatic debits, giving companies assurance that they are working correctly and safely.

    Enhanced Customer Experience

    In addition to the benefits for companies, digital authorization also provides a better experience for customers. The process is simple, quick, and secure. Customers no longer need to fill out forms or wait for confirmations by mail. Everything is arranged online, which suits the desires of the modern consumer.

    Moreover, the digital approach offers transparency: customers can immediately see which company is processing the authorization and for what purpose. This strengthens confidence in the process.

    Application Across All Sectors

    Digital authorization is not limited to a specific sector. From energy suppliers and gyms to charities and insurance companies, businesses across various industries benefit from this modern method. Even small entrepreneurs can easily transition and benefit from the advantages.

    The Future of Authorizations

    With the increasing digitization, digital authorization is a logical step. It makes business processes more efficient, provides customers convenience, and fits within the trends of fast and reliable online services. More organizations recognize that switching to digital authorization is not a luxury, but a necessity to remain competitive.

    The Benefits of Digital Direct Debit Authorization with Bluem

    Bluem makes digital direct debit authorization simple and efficient for businesses. With a user-friendly solution and various handy features, Bluem provides everything you need to optimize your payment processes.

    • Fast and Ready to Use

    With Bluem, you can get started immediately. Whether you run a webshop or provide business services, integrating digital authorizations is smooth via API or plugin. This way, you can easily add authorization options to your platform.

    • Flexible Integration Options

    We understand that every company is unique. That is why you can choose from multiple connection options such as an API, a plugin, or an online dashboard. This makes it easy to seamlessly tailor digital direct debit authorization to your existing systems and workflow.

    • Automated Reminders

    Bluem’s system supports businesses in managing payments by automatically sending reminders. Customers are notified on time when a payment deadline is approaching or if a payment has been missed. This helps prevent payment backlogs and promotes a healthy cash flow.

    • Personalized Communication

    You can fully customize authorization emails to match your own brand style and tone of voice. This ensures a recognizable and professional appearance, increasing customer trust.

    • Comprehensive Reporting

    Insight is essential for a smooth payment process. Bluem offers extensive reporting capabilities that provide a complete overview of active and completed authorizations. This way, you can work administratively efficiently and better respond to your customers’ payment behavior.

    • Authorization Page in Your Own Style

    A reliable appearance is crucial in the payment process. With Bluem, you can customize the authorization page to match your own brand style. Customers immediately see they are dealing with a trusted party, increasing the chance of successful authorizations.

    Conclusion

    With Bluem’s solutions, you can easily integrate digital direct debit authorization into your business operations. You offer customers a safe, efficient experience and benefit from a streamlined and reliable process yourself. Choose Bluem and get the most out of your digital payment options.

  • Comment protégeons-nous notre organisation contre les fraudes en ligne ?

    Comment protégeons-nous notre organisation contre les fraudes en ligne ?

    Fraud remains a stealthy danger for companies in the Netherlands. Although many organizations have confidence in their own measures, research points to a hard reality: fraud affects an overwhelming majority of businesses and causes serious financial damage.

    Fraud Statistics in 2023/2024

    The annual fraud research shows that no less than 69% of companies in 2023/2024 faced fraud attempts. In 91% of the cases, this led to actual harm. These figures make clear that fraud is not a marginal issue but a widespread risk. Moreover, the financial consequences are significant:

    • 55% of the damage cases resulted in a loss of more than €50,000.
    • 16% of the damage cases exceeded €200,000.
    • In cases of internal fraud, 2% of companies suffered more than €1 million in damage, while for external fraud, this rose to 5%.

    These figures underline that the impact of fraud is not only widespread but also poses a serious threat to the financial health of organizations.

    Source: Allianz Trade.

    The Dangerous Gap between Perception and Reality

    A notable conclusion from the research is the difference between how companies perceive fraud and its actual impact. 95% of companies are satisfied with their existing measures and security protocols. Yet, a majority indicates that fraud as a threat is growing. However, many organizations continue to believe they are not at great risk themselves.

    This sense of security is often unjustified. The figures show that the chance of becoming a victim is significant, with potentially devastating consequences. This contrast between confidence in self-measures and the real risks points to a false sense of security.

    Uninsured against Fraud: A Risk Many Companies Take

    Another concerning aspect is that less than half of the companies have insurance against fraud. As a result, organizations often rely entirely on their own reserves when affected. This can be especially disastrous for small and medium-sized businesses, as they often have fewer resources to absorb such losses.

    Tools to Prevent Fraud

    While fraud can be difficult to detect due to sophisticated methods, there are various measures companies can take to reduce their risk:

    1. Contrôle du nom IBAN: The IBAN-Name Check compares the beneficiary’s name with the name known by the bank for the specified IBAN number. This helps prevent payments to incorrect accounts and minimizes the risk of fraud and errors when transferring money.
    2. Verification de l'identité: Identity verification ensures that a customer’s identity is checked securely and reliably. This can be done through a combination of documents, biometric data, and other verification methods. This way, you know who you are dealing with, and the chance of fraud is reduced because you can verify the customer’s authenticity and prevent unauthorized access.
    3. Digital Authorization: Digital authorization offers extra assurance when granting authorization, preventing unauthorized debits. By using legally valid digital authorization through the beneficiary’s bank, you reduce the chance of fraud. This adds an extra layer of control because only verified authorizations are accepted.

    Conclusion

    Fraud is a growing danger that companies should not underestimate. Trust in existing measures often proves unjustified, and the financial damage can be substantial. Companies that invest in prevention and protection now can better equip themselves against this threat and avoid becoming one of the victims losing millions annually. Bluem offers a comprehensive package of services, such as IBAN-Name check, IDIN, ID-scanning, and direct debit authorization, which reduce organizations’ risk of fraud.

  • The Impact of Digitalization on Businesses

    The Impact of Digitalization on Businesses

    Digitalization is one of the driving forces behind growth, efficiency, and innovation. Recent research by CBS shows that nearly 91 percent of Dutch companies have undertaken digitalization initiatives in recent years. The main motivation for this is the expected productivity and efficiency gains. However, digitalization is not without challenges. Many companies encounter obstacles, such as high costs and a shortage of qualified personnel.

    Digitalization and Productivity Growth

    Increasing productivity is a key reason for companies to further digitalize. About 53 percent of companies cited this as the primary reason. By embracing ICT and digital technologies, they can streamline their work processes and get more out of their available resources. Larger companies seem to benefit the most: 67 percent of large companies experienced a positive impact, compared to 44 percent of smaller companies. In sectors such as retail and business services, this impact was even more evident.

    Sectoral Differences in Digitalization

    The degree and impact of digitalization vary by sector. Retailers, with over 65 percent, most often indicated that digitalization positively contributes to their growth and development. In the information and communication sector, where 20 percent of companies reported a significant positive impact, digitalization also plays an important role. On the other hand, digitalization lags in sectors like hospitality, where slightly more than 18 percent did not undertake digitalization initiatives.

    Barriers to Digitalization

    Despite the advantages of digitalization, companies experience various barriers. A lack of skilled staff is the main obstacle for more than 20 percent of businesses, especially in sectors such as real estate leasing and trading. Companies struggle to find specialized personnel who can guide and implement digital transformation. Additionally, nearly 18 percent of companies cite high costs as a barrier, especially for small enterprises.

    Positive Experiences and Challenges

    Digitalization does not have the same impact on all companies. Over a third of businesses notice little to no impact from their digital initiatives. Yet, 54 percent of companies experienced a (very) positive impact on growth and development in the past 12 months. This shows that, while digitalization offers opportunities, the benefits highly depend on the extent to which a company is prepared and supported in this transition.

    How to Start Digitalizing?

    For companies looking to start digitalizing, there are various practical steps that can be implemented in the short term. Here are three ways to begin digitalizing that offer relatively simple solutions:

    Digital Payments and Direct Debit Authorization: By switching to digital payment systems, transactions can be executed faster and more securely.

    Digital Onboarding: including ID scanning and PEP/sanction list checks, ensures fast and secure verification of new customers and employees. These automated processes reduce the risk of fraud and ensure companies meet compliance requirements.

    Signature numérique: Implementing digital signatures accelerates the approval process of documents and contracts. Additionally, digitalizing contracts makes contract management and storage simpler and safer.

    Conclusion

    Starting with digitalization doesn’t have to be complicated. With the right strategy and tools, companies can already benefit from the many advantages digitalization has to offer in the short term. Services like those from Bluem make it easy to implement digital solutions, enabling companies to quickly respond to the changing market demands and strengthen their competitive position. By starting to digitalize now, companies can prepare for a future where technology plays a central role in their success.

    Source: CBS & Conjunctuurenquête Nederland