Auteur: Bluem Team

  • The Future of Online Identification: Secure & User-Friendly

    De toekomst van online identificatie: veilig en gebruiksvriendelijk

    We are doing more and more online: shopping, banking, and even important tasks such as getting a mortgage or registering for an event. However, these developments also bring new challenges. How can you as a business owner be sure that the person on the other side of the screen is truly who they say they are? And how do you ensure that this process remains safe and user-friendly?

    Online identification is the solution and forms the backbone of the modern digital economy. Services like iDIN and Checkin.com make it possible to verify identities reliably.

    Why online identification is becoming increasingly important

    With the growth of digital services, the need for secure and reliable authentication is also increasing. A copy of a passport is often vulnerable to fraud and phishing. Moreover, consumers want convenience: they expect quick access without endless forms or complexity. The presence of the user is no longer required – everything can be handled digitally in one seamless flow.

    Online identification services solve these problems by:

    • Security: Strong authentication prevents unauthorized access.
    • Privacy: Data is only shared with the user’s consent.
    • Speed: Simplifies processes and ensures an efficient user experience.
    • Certainty: Provides reliable verification of identities, giving both businesses and users confidence in the process.

    iDIN: The pioneer in secure online identification

    iDIN, developed by Currence, is one of the most widely used online identification services in the Netherlands. It uses the trusted login methods of banks, providing a high level of security and reliability.

    Hoe werkt iDIN?

    • The user selects iDIN as the identification method in an online environment.
    • Through their bank environment, the consumer logs in.
    • The consumer grants permission to share personal data.
    • The bank confirms the identity and shares this data securely with the provider, only with the user’s consent.

    With applications such as age verification (for example, when selling alcohol) and account creation, iDIN is already a proven solution. It provides entrepreneurs certainty about customer data and meets legal requirements.

    ID-Scanning: A Reliable Method for Online Identification

    ID-Scanning is an online identification method using a scan or photo of your identity document (such as a passport, driver’s license, or ID card). This approach is ideal for applications where a high level of certainty about identity is required, such as at financial institutions, landlords, or other services.

     How does ID-Scanning work?

    With ID-Scanning, identity documents can be digitally captured and checked, giving businesses assurance about their customers’ identities. The process begins with uploading a clear digital copy of an identity document, such as a passport, ID card, or driver’s license. The authenticity of the document is then analyzed using advanced technology, including artificial intelligence (AI) and machine learning. This technology checks security features such as watermarks and holograms and compares the data with relevant databases.

    If necessary, an additional manual review by a specialist can be conducted to identify irregularities or eliminate doubt. Thanks to this combination of automation and expert control, ID-Scanning offers a secure and efficient way to verify identities, providing confidence for both businesses and users. ID-Scanning is an efficient and safe method for verifying identities and is widely used in various sectors.

    What does this mean for your business?

    For entrepreneurs, it is clear: online identification is not a luxury but a necessity. Whether you work in e-commerce, healthcare, or finance, reliable and secure identification strengthens your customers’ trust and protects your business against risks.

    With identification solutions like iDIN and Checkin.com, you can easily adapt to this trend. Invest now in the future of online identification and prepare your business for a safe and customer-friendly digital world.
  • Hoe u uw bedrijf in 2025 digitaal kunt digitaliseren

    Hoe u uw bedrijf in 2025 digitaal kunt digitaliseren

    The Advantages of Digitalization

    1. Increased Productivity

    One of the main reasons for companies to digitalize is the gain in productivity. According to the McKinsey report, 56 percent of companies indicate that integrated digital technologies have significantly improved their work processes. By automating processes such as inventory management, customer service, and administration, organizations can maximize their resources. Especially in sectors like retail and business services, these improvements are significant.

    1. Better Customer Orientation

    Alongside productivity, digitalization enables companies to serve their customers better. With advanced data analysis tools, businesses can better understand and respond to customer behavior. More than 62 percent of companies in the retail sector reported that digital technologies helped them personalize customer interactions and increase loyalty.

    Challenges of Digitalization

    1. Lack of Qualified Personnel

    A shortage of skilled personnel remains a major challenge. The study reveals that 24 percent of companies struggle to find employees with the right digital skills. Smaller companies particularly suffer from this, as they have fewer resources to attract talent.

    1. Implementation Costs

    High costs are mentioned by 19 percent of companies as an obstacle to digitalization. For smaller companies, investments in software, hardware, and training often pose a significant hurdle.

    Hoe start je met digitaliseren?

    For companies that want to start digitalizing, there are various practical steps that can be implemented in the short term. Here are three ways to begin digitalizing that offer relatively simple solutions:

    Digital Payments and Direct Debits: By switching to digital payment systems, transactions can be processed more quickly and securely.

    Digital Onboarding: including ID scanning and PEP/sanction list checks, ensures quick and secure verification of new customers and employees. These automated processes reduce the risk of fraud and ensure that companies meet compliance requirements.

    Digital Signing: Implementing digital signatures speeds up the approval process for documents and contracts. Additionally, digitalizing contracts simplifies and secures contract management and storage.

    Conclusie

    Digitalization in 2025 is not only about technology but also about strategy. By choosing the right tools and partners, companies can tackle both the opportunities and challenges of digitalization. Companies that invest timely in digital transformation lay the groundwork for a competitive and future-proof organization.

    Source: McKinsey & Company Digital Strategy Insights 2024

  • 4 hulpmiddelen die elke HR-afdeling in 2025 nodig heeft

    4 hulpmiddelen die elke HR-afdeling in 2025 nodig heeft

    The world of Human Resources is changing rapidly. What was once an administrative role is now a strategic function crucial to an organization’s success. Smart technology plays a key role in this transformation. With the right tools, you can work more efficiently and provide a unique employee experience. Bluem develops innovative solutions that meet the needs of modern HR teams. Here are four essential tools that will elevate your HR department.

    1. iDIN: Secure and Fast Identification

    Identifying employees, especially during onboarding, can be a time-consuming process. iDIN simplifies this by enabling secure and user-friendly digital identification. No more hassle with physical documents; everything flows smoothly and completely online.

    Benefits of iDIN:

    • Accelerate onboarding with digital identification.
    • Reduce paperwork and contribute to a sustainable workflow.
    • No need to ask for a passport copy.
    • Secure sensitive processes like contract signing.
    1. Real-Time IBAN-Name Check: Eliminating Payment Errors

    Entering bank details is error-prone and can lead to costly problems. The Real-Time IBAN-Name Check prevents these risks by instantly verifying if the data is correct. This minimizes errors and increases payment reliability.

    What does this tool offer?

    • Automatic verification of bank details without extra effort from employees.
    • Reduce risks of fraud and incorrect payments.
    • Save time by eliminating manual checks.
    • Bank card copy unnecessary.
    1. Scrive eSign: Smart and Digital Signing

    Signing documents no longer has to be a time-consuming task. With Scrive eSign, you can have contracts and other important papers digitally signed, legally binding and compliant with international standards.

    Why choose digital signing?

    • Reduce administrative hassle and make the process more efficient.
    • Work flexibly, even when participants are not physically present.
    • Ensure seamless onboarding, even remotely.
    1. PEP and Sanction List Checking: Fully Compliant Working

    In sectors where regulations play a major role, such as financial services, it is crucial to screen candidates. With Bluem’s automated PEP and Sanction List Checking, you ensure new employees comply with anti-money laundering laws and other requirements, ensuring they do not appear on a sanctions list.

    This tool offers:

    • Immediate screening on international sanctions lists and PEPs.
    • Real-time insights to timely signal risks.
    • Assurance that you comply with all laws and regulations.

    Transform the HR Department

    Efficiency, security, and compliance are the pillars of a modern HR strategy. With tools like iDIN, the Real-Time IBAN-Name Check, Scrive eSign, and PEP and Sanction List Checking, you can digitize outdated processes, minimize risks, and provide a streamlined employee experience.

    Bluem’s solutions help you be less dependent on paperwork and manual actions, optimally preparing your HR department for the future and making a lasting impression on employees and candidates.

  • KYC, wat is dat en waarom is het belangrijk?

    KYC, wat is dat en waarom is het belangrijk?

    In recent years, KYC (Ken uw klant) has evolved into a crucial business process within organizations. The aim? To thoroughly understand customers in order to minimize risks of financial crime and safeguard the integrity of the financial system.

    What is KYC?

    KYC, or “know your customer,” refers to processes by which financial institutions verify the identity of their clients and assess potential risks. Through thorough investigation, institutions can determine if a client is involved in criminal activities, such as money laundering, fraud, or financing terrorism. This process not only protects the financial institution but also the broader financial system.

    The KYC process includes:

    • Identification and verification of clients and any ultimate beneficial owners (UBOs).
    • Creating a complete customer profile.
    • Determining the purpose and nature of the customer relationship.
    • Identifying and assessing risks.
    • Analyzing transactions.
    • Accepting or rejecting clients based on research findings.

    KYC and CDD: What is the difference?

    KYC serves as an overarching principle that encompasses Customer Due Diligence (CDD) and Anti-Money Laundering (AML). Although the terms are often used interchangeably in practice, CDD specifically focuses on customer due diligence within the broader KYC framework.

    Importance of KYC

    Financial institutions such as banks and insurers are legally required to protect their services from criminal use. This means they must recognize and assess potential risks to prevent misuse.

    Complying with KYC rules not only contributes to the integrity of the financial system but also protects the reputation of institutions. Furthermore, it fosters trust in the economy, which is essential for stability.

    Legislation and Obligations

    In the Netherlands, KYC obligations are enshrined in various laws, including:

    1. The Anti-Money Laundering and Anti-Terrorist Financing Act (Wwft): Focuses on detecting and reporting unusual transactions.
    2. The Sanctions Act: Prevents business relations with sanctioned parties.
    3. The Financial Supervision Act (Wft): Provides oversight of the financial sector.

    This legislation is based on international recommendations from the Financial Action Task Force (FATF). Financial institutions are required to report unusual transactions to the Financial Intelligence Unit (FIU).

    Enforcement and Penalties

    In recent years, various institutions have been fined for shortcomings in KYC processes. For example, ING paid a settlement of 775 million euros for negligence in money laundering prevention, and Rabobank was fined a million euros for inadequate customer records.

    The Solutions by Bluem

    Bluem understands the challenges of KYC and offers various solutions to make the process more efficient, secure, and customer-friendly.

    Verifying the accuracy of an IBAN number is essential to prevent payment issues. With Bluem’s IBAN-Name Check, you can quickly and easily ensure that the account holder’s name matches the specified IBAN number. This reduces the risk of fraudulent transactions and mistakes.

    Bluem offers digital verification options allowing you to quickly and reliably confirm the identity of new clients. This helps meet legal requirements and reduces the risk of identity fraud.

    Protect vulnerable individuals from unwanted situations and contracts. The person should not independently enter into agreements or make financial decisions. In practice, it involves individuals suffering from mental disorders, overspending, or addictions. With Bluem’s CCBR check, a company prevents issues later on, including the financial damage associated with reversing all (null) actions.

    To comply with legal obligations related to anti-money laundering practices, it is crucial to conduct thorough customer checks. Bluem’s AML solution automates this process by screening clients against sanction lists, PEP lists (Politically Exposed Persons), and other relevant data sources. This helps companies to comply with regulations and minimize integrity risks.

    Conclusie

    KYC is indispensable in the fight against financial-economic crime. For financial institutions, this not only means fulfilling legal obligations but also contributing to a reliable and secure financial system.

  • Waarom steeds meer bedrijven overstappen op iDIN

    Waarom steeds meer bedrijven overstappen op iDIN

    Met de groei van digitale diensten wordt het steeds belangrijker voor ondernemers om klanten snel en betrouwbaar te identificeren. Tegelijkertijd verwachten consumenten dat dit proces veilig en gebruiksvriendelijk is. iDIN iDIN biedt een innovatieve oplossing die perfect aan deze eisen voldoet. Waarom kiezen steeds meer bedrijven voor iDIN? En wat maakt deze identiteitsdienst onmisbaar voor u als ondernemer?

    Wat is iDIN En hoe werkt het?

    iDIN is een online identificatiedienst die gebruikmaakt van de veilige aanmeldmethoden van banken. Gebruikers kunnen hun identiteit bevestigen en hun persoonlijke gegevens delen met bedrijven via iDIN, zonder dat ze nieuwe accounts hoeven aan te maken. De kracht van iDIN ligt in het vertrouwen dat gebruikers al in hun bank hebben, gecombineerd met een eenvoudige gebruiksprocedure.

    Hoe werkt het?

    1. De gebruiker kiest bij een online dienst of webshop iDIN als identificatiemethode.
    2. Door middel van een vertrouwde inlogomgeving van hun eigen bank (zoals bij online banking) bevestigt de gebruiker hun identiteit.
    3. Gegevens zoals naam, adres en geboortedatum worden veilig gedeeld met het bedrijf, uitsluitend met de expliciete toestemming van de gebruiker.

    Waarom kiezen bedrijven voor iDIN?

    1. Aanwezigheid van klantidentiteit

    Als ondernemer wilt u er zeker van zijn dat uw klanten degenen zijn die zij beweren te zijn. Of het nu gaat om leeftijdsverificatie, identiteitscontroles tijdens gevoelige transacties of het aanmaken van een account – iDIN biedt een eenvoudige en betrouwbare oplossing. Op die manier voldoet uw bedrijf ook direct aan wettelijke vereisten zoals die voor de verkoop van alcohol of andere producten met een leeftijdsbeperking.

    Voorbeeld: PostNL test een systeem waarbij klanten met iDIN moeten aantonen dat ze ouder dan 18 zijn om alcohol te kunnen bezorgen. Dit maakt naleving van wet- en regelgeving eenvoudig en betrouwbaar.

    1. Gebruiksvriendelijkheid voor consumenten

    Een soepele klantenservice is essentieel voor conversie en klanttevredenheid. Met iDIN hoeven consumenten geen nieuwe wachtwoorden of accounts aan te maken. Ze gebruiken hun vertrouwde bankomgeving om hun identiteit te verifiëren. Dit verlaagt de barrières en zorgt voor een betere klantbeleving.

    1. Bescherming tegen fraude

    iDIN maakt gebruik van sterk authenticatie via de beveiligingssystemen van banken. Dit minimaliseert het risico op fraude en ongeoorloofde toegang. Voor ondernemers betekent dit minder risico en een groter niveau van vertrouwen in klantgegevens.

    1. Privacy en naleving

    iDIN is ontworpen met het privacygevoel van de consument in gedachten. Bedrijven ontvangen alleen de gegevens die nodig zijn voor een specifieke transactie, en de toestemming wordt expliciet gegeven door de gebruiker. Dit maakt iDIN niet alleen veilig, maar ook volledig compliant met de Algemene Verordening Gegevensbescherming (GDPR).

    Toepassingen van iDIN

    De veelzijdigheid van iDIN-identificatie maakt het geschikt voor verschillende sectoren. Hier zijn enkele voorbeelden:

    • Ouderlijk toezichtVerkopen van alcohol, tabak of andere producten die alleen voor volwassenen zijn bestemd.
    • Account aanmaken: Directe en veilige registratie van nieuwe gebruikers.
    • Financiële dienstenVoor het bevestigen van de identiteit bij leningaanvragen of bij verzekeringen.
    • VoetbalclubsVoor professionele voetbalclubs is het belangrijk om precies te weten aan wie ze een clubkaart verkopen.

    Hoe werkt iDIN?

    1. Kies voor iDIN als identificatiemethode: Wanneer u zich wilt identificeren op een website die iDIN ondersteunt, selecteert u de optie iDIN. Dit kan zijn bij een online winkel, overheidsdienst of verzekeringsmaatschappij.
    2. Selecteer uw bank: Nadat u iDIN hebt gekozen, wordt u doorgestuurd naar een scherm waar u uw bank kunt selecteren. Dit zijn meestal de grootste Nederlandse banken zoals ING, Rabobank, ABN AMRO, enz.
    3. Log in bij uw bank: Log dan in bij uw bank zoals u dat normaal ook zou doen voor online banking. Dit kan via de app van de bank op uw smartphone of met een fysiek beveiligingscode.
    4. Verifieer uw identiteit: Zodra u bent ingelogd, bevestigt uw bank uw identiteit bij de dienstverlener waar u zich wilt identificeren. Het is belangrijk dat uw bank geen gevoelige gegevens zoals uw rekeningnummer of saldo met de dienstverlener deelt; alleen de bevestiging van uw identiteit wordt doorgestuurd.

    Bereid voor de volgende stap?

    Met iDIN wordt uw bedrijf efficiënter, veiliger en klantvriendelijker. Of het nu gaat om het voldoen aan wettelijke vereisten, het verhogen van de conversieratio of het verbeteren van uw klantrelatie – met iDIN brengt u een bewezen oplossing in huis.

    Wilt u als ondernemer voorbereid zijn op de toekomst? Dan is iDIN de keuze om te focussen op vertrouwen en veiligheid in uw dienstverlening.

  • Waarom steeds meer organisaties beginnen met digitale autorisatie voor collecties

    Waarom steeds meer organisaties beginnen met digitale autorisatie voor collecties

    Organizations are constantly seeking ways to optimize their processes. Digital direct debit authorization is a solution that is increasingly being embraced. It enables companies and customers to quickly and easily arrange permissions for recurring payments or authorizations. But what makes this approach so appealing, and why are so many organizations switching?

    Wat is Digital Direct Debit Authorization?

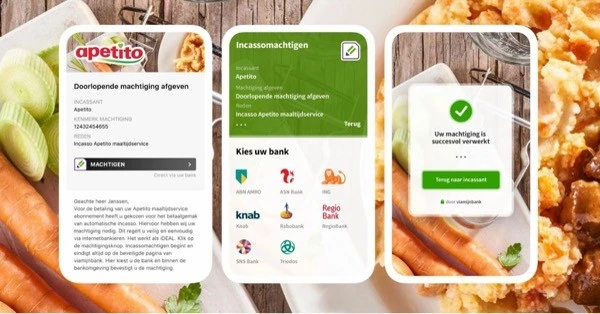
    Digital direct debit authorization is an online process that allows a customer to give an organization permission to automatically collect payments. This process is similar to an iDEAL transaction: the customer chooses their bank, gives approval, and the authorization becomes valid immediately. The traditional paperwork that used to be associated with authorizations is now a thing of the past.

    Benefits for Organizations

    More and more companies see the benefits of digital authorization. A key argument is the time savings. Where traditional authorizations could take days or even weeks due to mailing, processing, and manual checks, a digital authorization can be completed in just a few minutes.

    Additionally, digital authorization offers a greater degree of accuracy. Because the data is entered and processed directly through the customer’s bank, errors such as incorrect account numbers or missing information are virtually eliminated. This prevents administrative issues and improves the quality of the customer relationship.

    Another major advantage is compliance. Digital direct debit authorization complies with legal requirements and guidelines surrounding automatic debits, giving companies assurance that they are working correctly and safely.

    Enhanced Customer Experience

    In addition to the benefits for companies, digital authorization also provides a better experience for customers. The process is simple, quick, and secure. Customers no longer need to fill out forms or wait for confirmations by mail. Everything is arranged online, which suits the desires of the modern consumer.

    Moreover, the digital approach offers transparency: customers can immediately see which company is processing the authorization and for what purpose. This strengthens confidence in the process.

    Application Across All Sectors

    Digital authorization is not limited to a specific sector. From energy suppliers and gyms to charities and insurance companies, businesses across various industries benefit from this modern method. Even small entrepreneurs can easily transition and benefit from the advantages.

    The Future of Authorizations

    With the increasing digitization, digital authorization is a logical step. It makes business processes more efficient, provides customers convenience, and fits within the trends of fast and reliable online services. More organizations recognize that switching to digital authorization is not a luxury, but a necessity to remain competitive.

    The Benefits of Digital Direct Debit Authorization with Bluem

    Bluem makes digital direct debit authorization simple and efficient for businesses. With a user-friendly solution and various handy features, Bluem provides everything you need to optimize your payment processes.

    • Fast and Ready to Use

    With Bluem, you can get started immediately. Whether you run a webshop or provide business services, integrating digital authorizations is smooth via API or plugin. This way, you can easily add authorization options to your platform.

    • Flexible Integration Options

    We understand that every company is unique. That is why you can choose from multiple connection options such as an API, a plugin, or an online dashboard. This makes it easy to seamlessly tailor digital direct debit authorization to your existing systems and workflow.

    • Automated Reminders

    Bluem’s system supports businesses in managing payments by automatically sending reminders. Customers are notified on time when a payment deadline is approaching or if a payment has been missed. This helps prevent payment backlogs and promotes a healthy cash flow.

    • Personalized Communication

    You can fully customize authorization emails to match your own brand style and tone of voice. This ensures a recognizable and professional appearance, increasing customer trust.

    • Comprehensive Reporting

    Insight is essential for a smooth payment process. Bluem offers extensive reporting capabilities that provide a complete overview of active and completed authorizations. This way, you can work administratively efficiently and better respond to your customers’ payment behavior.

    • Authorization Page in Your Own Style

    A reliable appearance is crucial in the payment process. With Bluem, you can customize the authorization page to match your own brand style. Customers immediately see they are dealing with a trusted party, increasing the chance of successful authorizations.

    Conclusie

    With Bluem’s solutions, you can easily integrate digital direct debit authorization into your business operations. You offer customers a safe, efficient experience and benefit from a streamlined and reliable process yourself. Choose Bluem and get the most out of your digital payment options.

  • Hoe bescherm ik mijn organisatie tegen online fraude?

    Hoe bescherm ik mijn organisatie tegen online fraude?

    Frauduleus gedrag blijft een geheimzinnige dreiging voor bedrijven in Nederland. Hoewel veel organisaties vertrouwen hebben in hun eigen maatregelen, wijzen onderzoeken op een harde realiteit: fraude treft een overweldigende meerderheid van bedrijven en veroorzaakt ernstige financiële schade.

    Fraudestatistieken in 2023/2024

    De jaarlijkse frauderisearch toont aan dat niet minder dan 69% van de bedrijven In 2023/2024 werden er pogingen tot fraude geconstateerd. In 91% van deze gevallen leidde dit tot daadwerkelijke schade. Deze cijfers maken duidelijk dat fraude geen marginale kwestie is, maar een wijdverbreid risico. Bovendien zijn de financiële gevolgen aanzienlijk:

    • 55% van de schadegevallen Dit leidde tot een verlies van meer dan €50.000.
    • 16% De schadeclaims overtroffen €200.000.
    • In gevallen van intern fraude, 2% bedrijven De schade bedroeg meer dan €1 miljoen, terwijl voor externe fraude dit bedrag opliep tot 5%.

    Deze cijfers onderstrepen dat de impact van fraude niet alleen wijdverbreid is, maar ook een ernstige bedreiging vormt voor de financiële gezondheid van organisaties.

    Bron: Allianz Trade.

    De gevaarlijke kloof tussen perceptie en realiteit

    Een opmerkelijke conclusie uit het onderzoek is het verschil tussen hoe bedrijven fraude ervaren en de daadwerkelijke impact ervan. 95% van de bedrijven Ze zijn tevreden met hun bestaande maatregelen en beveiligingsprotocollen. Toch geeft een meerderheid aan dat fraude een groeiend probleem is. Veel organisaties geloven echter nog steeds niet dat zij zelf een groot risico lopen.

    Dit gevoel van zekerheid is vaak ongegrond. De cijfers tonen aan dat de kans om slachtoffer te worden aanzienlijk is, met potentieel verwoestende gevolgen. Deze tegenstelling tussen vertrouwen in eigen maatregelen en de werkelijke risico's wijst op een falsen gevoel van veiligheid.

    Onverzekerd tegen fraude: een risico dat veel bedrijven lopen

    Een ander zorgwekkend aspect is dat minder dan de helft van de bedrijven een verzekering tegen fraude heeft. Hierdoor zijn organisaties vaak volledig afhankelijk van hun eigen reserves wanneer ze getroffen worden. Dit kan vooral rampzalig zijn voor kleine en middelgrote bedrijven, omdat ze vaak minder middelen hebben om dergelijke verliezen te absorberen.

    Tools om fraude te voorkomen

    Hoewel fraude moeilijk te detecteren is vanwege geavanceerde methoden, zijn er verschillende maatregelen die bedrijven kunnen nemen om hun risico te verminderen:

    1. IBAN-naamcontrole: De IBAN-naamcontrole vergelijkt de naam van de begunstigde met de naam die de bank kent voor het specifieke IBAN-nummer. Dit helpt bij het voorkomen van betalingen naar onjuiste rekeningen en minimaliseert het risico op fraude en fouten bij het overmaken van geld.
    2. Identiteitsverificatie: Identiteitsverificatie zorgt ervoor dat de identiteit van een klant veilig en betrouwbaar wordt gecontroleerd. Dit kan worden gedaan door een combinatie van documenten, biometrische gegevens en andere verificatiemethoden. Op deze manier weet u wie u te maken hebt en wordt de kans op fraude verkleind, omdat u de authenticiteit van de klant kunt verifiëren en ongeautoriseerde toegang kunt voorkomen.
    3. Digitale autorisatie: Digitale autorisatie biedt extra zekerheid bij het verstrekken van autorisaties en voorkomt onbevoegde afschrijvingen. Door gebruik te maken van een juridisch geldige digitale autorisatie via de bank van de begunstigde, vermindert u de kans op fraude. Dit voegt een extra laag controle toe, omdat alleen geverifieerde autorisaties worden geaccepteerd.

    Conclusie

    Fraud is een groeiend gevaar dat bedrijven niet mogen onderschatten. Vertrouwen in bestaande maatregelen blijkt vaak ongegrond, en de financiële schade kan aanzienlijk zijn. Bedrijven die nu investeren in preventie en bescherming kunnen zich beter wapenen tegen deze dreiging en voorkomen dat zij een van de slachtoffers worden die jaarlijks miljoenen verliezen. Bluem biedt een uitgebreid pakket diensten aan, zoals IBAN-naamcontrole, IDIN, ID-scanning en autorisatie voor automatische incasso, waardoor organisaties minder risico lopen op fraude.

  • De impact van digitalisering op bedrijven

    De impact van digitalisering op bedrijven

    Digitalisering is een van de drijvende krachten achter groei, efficiëntie en innovatie. Recent onderzoek van CBS toont aan dat bijna 91 procent van de Nederlandse bedrijven in de afgelopen jaren digitale initiatieven heeft genomen. De belangrijkste reden hiervoor is de verwachte verbetering van de productiviteit en efficiëntie. Digitalisering brengt echter ook uitdagingen met zich mee. Veel bedrijven ondervinden obstakels, zoals hoge kosten en een tekort aan gekwalificeerd personeel.

    Digitalisering en productiviteitsgroei

    De verhoging van de productiviteit is een belangrijke reden waarom bedrijven verder willen digitaliseren. Circa 53 procent van de bedrijven noemde dit als de belangrijkste reden. Door ICT en digitale technologieën te gebruiken, kunnen ze hun werkprocessen stroomlijnen en meer uit hun beschikbare middelen halen. Grotere bedrijven lijken het meest te profiteren: 67 procent van de grote bedrijven ervoer een positief effect, tegenover 44 procent van kleinere bedrijven. In sectoren zoals retail en zakelijke dienstverlening was deze impact nog duidelijker.

    Sectorale verschillen in digitalisering

    De mate en impact van digitalisering verschilt per sector. Winkeliers, met meer dan 65 procent, gaven het meest vaak aan dat digitalisering een positieve bijdrage levert aan hun groei en ontwikkeling. In de informatie- en communicatiebranche, waar 20 procent van de bedrijven een significant positief effect rapporteerde, speelt digitalisering ook een belangrijke rol. Aan de andere kant is digitalisering achtergebleven in sectoren zoals de horeca, waar iets meer dan 18 procent geen digitale initiatieven heeft genomen.

    Belemmeringen voor digitalisering

    Ondanks de voordelen van digitalisering ervaren bedrijven verschillende obstakels. Een tekort aan gekwalificeerd personeel is het grootste probleem voor meer dan 20 procent van de bedrijven, vooral in sectoren zoals vastgoedverhuur en -handel. Bedrijven hebben moeite om gespecialiseerd personeel te vinden dat digitale transformatie kan begeleiden en implementeren. Bovendien geeft bijna 18 procent van de bedrijven hoge kosten aan als een obstakel, vooral voor kleine bedrijven.

    Positieve ervaringen en uitdagingen

    Digitalisering heeft niet dezelfde impact op alle bedrijven. Meer dan een derde van de bedrijven merkt nauwelijks of geen impact op hun digitale initiatieven. Toch ervaart 54 procent van de bedrijven in de afgelopen 12 maanden een (zeer) positieve impact op groei en ontwikkeling. Dit toont aan dat, terwijl digitalisering kansen biedt, de voordelen sterk afhangen van de mate waarin een bedrijf voorbereid en ondersteund is bij deze transitie.

    Hoe start je met digitaliseren?

    Voor bedrijven die op zoek zijn naar het digitaliseren van hun bedrijfsprocessen, zijn er verschillende praktische stappen die op korte termijn kunnen worden geïmplementeerd. Hieronder staan drie manieren om te beginnen met digitaliseren die relatief eenvoudige oplossingen bieden:

    Digitale betalingen en autorisatie voor directe debet: Door over te schakelen op digitale betalingssystemen kunnen transacties sneller en veiliger worden uitgevoerd.

    Digitale onboarding: inclusief ID-scanning en verificatie van de PEP-/sanctielijst, zorgt ervoor dat nieuwe klanten en medewerkers snel en veilig worden gecontroleerd. Deze geautomatiseerde processen verminderen het risico op fraude en zorgen ervoor dat bedrijven voldoen aan de compliance-vereisten.

    Digitale handtekeningDe implementatie van digitale handtekeningen versnelt het goedkeuringsproces van documenten en contracten. Bovendien maakt het digitaliseren van contracten het beheer en de opslag van contracten eenvoudiger en veiliger.

    Conclusie

    Het starten met digitalisering hoeft niet ingewikkeld te zijn. Met de juiste strategie en tools kunnen bedrijven al op korte termijn profiteren van de vele voordelen die digitalisering biedt. Diensten zoals die van Bluem maken het eenvoudig om digitale oplossingen te implementeren, waardoor bedrijven snel kunnen reageren op de veranderende marktvraag en hun concurrentiepositie kunnen versterken. Door nu te beginnen met digitaliseren, kunnen bedrijven zich voorbereiden op een toekomst waarin technologie een centrale rol speelt in hun succes.

    Bron: CBS & Conjunctuurenquête Nederland